The lie that keeps on giving
Unless you’re a multi-millionaire, you are going to have to watch your retirement savings, but Treasury thinks differently.
For years, Australians have been told a simple story about retirement: retirees are too cautious, they're not spending their superannuation, and they're leaving behind large nest eggs when they die. The solution, we're told, is to encourage people to draw down their savings faster or to invest in products such as annuities and retirement income products.
The problem is that this narrative rests heavily on a statistic that deserves far more scrutiny than it receives.
A Treasury Retirement Income Review found that members of one large superannuation fund died with around 90% of the superannuation balance they held at retirement. That finding has since been repeatedly cited as evidence that retirees are underspending their savings and need help overcoming their reluctance to spend.
But there is a crucial catch. It’s not true.
The review's finding was based on data from a single, unidentified, large super fund. Critics have long questioned whether the fund's membership was representative of the broader Australian population, particularly given that large balances are often concentrated among a relatively small segment of retirees.
Take our reader poll below – What’s your attitude to your superannuation / retirement savings?
The real truth
When we look at the retirement savings of ordinary Australians, a very different picture emerges.
The latest available age-based superannuation statistics show that the median super balance for Australians aged 65 to 69 is around $195,000. In other words, half of Australians entering retirement have less than this amount. Even for those aged 60 to 64, the median balance is only around $201,000.
These are not balances that allow people to live a lavish retirement, especially as living costs skyrocket.
Nor are they balances that make it easy to absorb the growing financial risks that come with ageing.
Older Australians are increasingly expected to fund private health insurance, out-of-pocket healthcare costs, dental expenses, home modifications, assistive technologies, residential aged care contributions, and in-home care services.
While the Age Pension provides an essential safety net, many retirees understand that their superannuation may need to last decades and help cover expenses that are difficult to predict. The fear of running out of money is not irrational. It reflects the reality of longer life expectancy and rising care costs.
Yet policy debates continue to focus on ways to encourage retirees to spend more as if we are all multi-millionaires – good luck to you if you are!
Successive governments and regulators have promoted the development of retirement income products on the basis that retirees are holding onto too much of their super. The assumption is that most people could enjoy a higher standard of living if they drew down their savings more quickly.
That may be true for retirees with very large account balances.
It is far less convincing for everyday Australians.
For many retirees, superannuation is not a vehicle for intergenerational wealth transfer. It is a contingency fund. It represents protection against ill health, aged care costs, the loss of a partner, housing repairs and the simple uncertainty of not knowing whether retirement will last 10 years or 30.
Research challenging Treasury's conclusions found that many retirees do in fact draw down their super significantly over time, with balances often reduced substantially or exhausted altogether as people age – caravan anyone?
ASFA analysis argued that some studies contained survivorship bias, overstating the extent to which retirees retain their savings because they focused on those still alive and still holding superannuation assets.
This matters because policy narratives shape policy responses.
If governments assume Australians are retiring with large balances and dying wealthy, the focus naturally turns to spending more. If the reality is that most retirees have relatively modest savings and legitimate concerns about future health and aged care costs, then the priority should be helping people build and protect their retirement savings rather than encouraging them to spend them faster.
The real story is not that retirees are hoarding riches.
The real story is that most Australians enter retirement with modest superannuation balances and face considerable uncertainty about the costs that lie ahead.
Until that reality is acknowledged, the claim that retirees are dying with 90 per cent of their super may remain what it has become in Australian retirement policy – a lie that is only serving those who want to separate retirees from their hard-earned savings.
If you feel strongly about protecting super, join our retirement income and superannuation campaign today. Alternatively, share this story with family and friends on Facebook or by email.


Thousands of Australia-wide discounts
Exclusive offers and savings across dining, shopping, gift cards, and more – all in the EAT | PLAY | SAVE app.
Members save 10% on Travel Insurance*
National Seniors members receive a 10% discount on travel insurance policies*.
Financial Information Consultant
Speak to a real person and receive up-to-date information on retirement planning, superannuation, and more!
Branches
Expand your social circle, enjoy social events, day trips, guest speakers, and meet like-minded members.
Exclusive Travel Discounts
Save on tours, cruises, and holidays with exclusive discounts on National Seniors Travel.
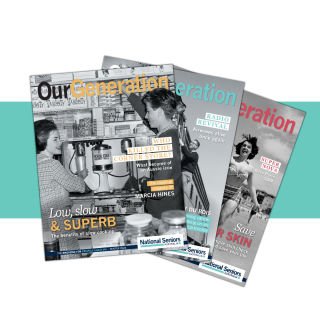
Our Generation Digital Magazine
Receive a yearly subscription to Our Generation Digital Magazine.
The Good Guys Commercial
Members enjoy exclusive access to The Good Guys Corporate Benefits. Save on small and large appliances as well as technology.
Advocacy & Research
Your membership directly funds our advocacy and research work fighting issues that affect you.
Competitions
Access exclusive member-only weekly competitions including books, DVDs, CDs, movie tickets and more.
Discounts
In addition to the discounts app, members can save thousands on eGift Cards and other discounted products.
*The discount applies to the total National Seniors travel insurance premium and is for National Seniors Australia members only. Discounts do not apply to the rate of GST and stamp duty or any changes you make to the policy. AGA has the discretion to withdraw or amend this discount offer at any time. This discount cannot be used in conjunction with any other promotional offer or discount.
For Travel Insurance policies purchased before 8 September 2026
National Seniors Australia Ltd ABN 89 050 523 003, AR 282736 is an authorised representative of nib Travel Services (Australia) Pty Ltd (nib), ABN 81 115 932 173, AFSL 308461 and act as nib's agent and not as your agent. This is general advice only. Before you buy, you should consider your needs, the Product Disclosure Statement (PDS), Financial Services Guide (FSG) and Target Market Determination (TMD) available from us. This insurance is underwritten by Pacific International Insurance Pty Ltd, ABN 83 169 311 193.
For Travel Insurance policies purchased on or after 8 September 2026
National Seniors Australia Ltd ABN 89 050 523 003, AR 282736, is an authorised representative of AWP Australia Pty Ltd, ABN 52 097 227 177, AFSL 245631, trading as Allianz Global Assistance (AGA), and acts as AGA's agent and not as your agent. nib Travel Services (Australia) Pty Ltd (nib), ABN 81 115 932 173, AFSL 308461 acts as third party administrator on behalf of AGA, managing claims, complaints, enquiries and sales. This is general advice only. Before you buy, you should consider whether the product is appropriate for you, the Product Disclosure Statement (PDS), Financial Services Guide (FSG) and Target Market Determination (TMD) is available from us. This insurance is underwritten by Pacific International Insurance Pty Ltd, ABN 83 169 311 193, AFSL 523921.