Transition to retirement: How it Can Help Clients Ease into Retirement
Retirement does not always have to mean stopping work completely
Sponsored Story
For many Australians, the transition to retirement can be gradual. Clients may choose to reduce their working hours, move into a less demanding role or continue working for several years while making the most of their superannuation.
A Transition to Retirement (TTR) strategy can potentially help clients manage this transition and make better use of their superannuation in the years leading up to retirement.
1. Reducing working hours and using superannuation to supplement income
One of the potential benefits of TTR is that it can allow clients to reduce their working hours while using some superannuation pension to supplement the resulting reduction in employment income.
For example, a client who has traditionally worked five days a week may decide to reduce their working week to three or four days.
Employment income would generally reduce, but a TTR income stream could potentially provide additional income to help bridge some of the difference.
This can provide a more gradual transition from full-time employment to retirement.
Potential benefits
1. A gradual transition into retirement
Reducing working hours can provide clients with a gradual transition from full-time employment towards retirement.
Rather than moving directly from full-time employment to full retirement, clients can gradually reduce their working commitments while maintaining some employment income.
This can provide more time for family, travel, hobbies or other interests while maintaining a connection to the workforce.
2. Supplementing employment income
A TTR income stream can provide an additional source of regular income when employment hours and salary are reduced.
For clients aged 60 or over, TTR pension payments are generally tax-free, subject to the applicable rules.
This can potentially make it easier for clients to reduce their working hours without experiencing the full financial impact of a reduction in salary.
3. Continuing to receive superannuation contributions
Clients who continue working may continue to receive compulsory employer superannuation contributions. Additional personal contributions are also available to these clients if certain requirements are met.
Depending on the circumstances, these contributions can help replenish some of the superannuation being withdrawn through the TTR strategy.
Potential disadvantages
1. Reduced superannuation balance
Accessing superannuation before fully retiring means there may be less capital available later in retirement.
The long-term impact can depend on the amount withdrawn, investment performance, ongoing contributions and the length of time before full retirement.
2. Potential impact on future retirement income
Withdrawals made through a TTR strategy can affect the amount of superannuation available in later retirement.
For clients with a long retirement horizon, withdrawing superannuation earlier may have an impact on the amount available to generate retirement income in the future.
3. Other financial circumstances need to be considered
A TTR strategy can interact with other areas of a client's financial position.
For example, consideration may need to be given to taxation, government benefits, superannuation insurance arrangements, investment strategy and overall household cash flow.
These factors should generally be considered before implementing a TTR strategy.
2. Continuing to work while using tax savings to build superannuation
A TTR strategy does not necessarily require clients to reduce their working hours. Another approach is for clients to continue working at the same capacity while making additional contributions to superannuation, such as through salary sacrifice, and using a TTR income stream to assist with their cash flow.
The objective can be to direct more employment income into superannuation while using TTR payments to help maintain the client's desired level of cash flow.
For some clients, this may provide a tax-effective way of building retirement savings during the years immediately before retirement.
Potential benefits
1. Potentially increasing superannuation savings
Additional contributions can increase the amount clients have available when they eventually retire.
Keeping additional money invested within superannuation may also provide the opportunity for investment returns to contribute to retirement savings.
Investment returns are not guaranteed, however, and the value of investments can rise and fall.
2. Potential tax benefits
Concessional contributions, including eligible salary sacrifice contributions, are generally taxed at a concessional rate within superannuation, subject to applicable rules and contribution caps.
For clients whose marginal tax rate is higher than the tax rate applying to concessional superannuation contributions, additional concessional contributions may potentially reduce their overall income tax liability.
The actual tax outcome will depend on the client's individual circumstances.
3. Continuing to work while strengthening retirement savings
This approach can allow clients to continue working at the same capacity while deliberately increasing their retirement savings.
It may be particularly relevant for clients who intend to continue working for several years and wish to strengthen their financial position before retirement.
Potential disadvantages
1. Reduced take-home income
Making additional salary sacrifice contributions generally reduces the amount of employment income received as cash.
A TTR income stream may potentially be used to supplement cash flow, but the strategy needs to be carefully structured to ensure the client's income requirements can be met.
2. Contribution caps apply
Superannuation contributions are subject to applicable contribution caps and eligibility requirements.
Exceeding the relevant limits can have tax consequences, so contribution levels need to be monitored carefully.
Existing contributions or other circumstances should also be taken into consideration when determining how much additional money can be contributed to superannuation.
3. The strategy can be complex
There are several variables that need to be considered, including:
- employment income;
- personal marginal tax rate;
- superannuation balance;
- total superannuation balance;
- existing contributions;
- past contributions;
- additional contribution levels;
- TTR pension payments;
- investment returns;
- household expenditure; and
- expected retirement income needs.
A strategy that may be appropriate for one client may not be appropriate for another.
Is Transition to Retirement appropriate for every client?
There is no single TTR strategy that is appropriate for every client.
Factors such as age, employment income, superannuation balance, taxation position, contribution history, investment strategy, household expenditure and retirement objectives can all influence whether a TTR strategy is appropriate.
It is also important to consider what happens after the client eventually stops working.
Superannuation may need to provide an income for many years throughout retirement. Consequently, decisions made in the years immediately before retirement can have long-term implications.
A TTR strategy is therefore generally best considered as part of a broader retirement plan, rather than simply as a tax strategy.
Why personal financial advice can be important
General information about Transition to Retirement can help clients understand how a TTR strategy works. However, general information cannot determine whether a particular strategy is appropriate for an individual client.
Personal financial advice can consider the client's individual circumstances and model different scenarios based on their goals and objectives.
For example, an adviser may compare the potential outcomes of:
- continuing to work full-time;
- reducing working hours;
- increasing superannuation contributions;
- commencing a TTR income stream;
- delaying retirement; or
- combining employment income with superannuation pension.
This can help clients understand the potential impact of different strategies on their current income, superannuation balance and future retirement income.
It can also help identify potential issues that may not be obvious when considering TTR in isolation.
Complimentary 60-minute Retirement Health Check with Amber Wealth
Clients approaching retirement may benefit from reviewing their financial position before making significant decisions about work, superannuation or retirement income.
Amber Wealth offers a complimentary 60-minute Retirement Health Check for clients who would like to discuss their retirement position and understand some of the areas that may warrant further consideration.
The Health Check can provide an opportunity to discuss:
- superannuation;
- retirement income;
- additional contributions;
- tax considerations;
- reducing working hours;
- transitioning into retirement; and
- potential retirement planning strategies.
To arrange a complimentary 60-minute Retirement Health Check:
Amber Wealth
📞 (03) 9964 0718
📍 Suite 9, Level 1, 214 Bay St, Brighton VIC 3186
The Health Check is an initial discussion and does not constitute personal financial advice.
Important information
This article provides general information only and does not take into account any individual's personal objectives, financial situation or needs. It is not personal financial advice.
Before implementing a Transition to Retirement strategy, clients should consider whether the information is appropriate for their circumstances and, where appropriate, seek personal financial advice from a qualified financial adviser.
Superannuation, taxation and government benefit rules can change. Individual circumstances can also produce different outcomes. Current information and appropriate professional advice should therefore be considered before making financial decisions. Adam Sobczak and Amber Wealth Pty Ltd are Authorised Representatives of Lifespan Financial Planning Pty Ltd AFSL 229892.

Thousands of Australia-wide discounts
Exclusive offers and savings across dining, shopping, gift cards, and more – all in the EAT | PLAY | SAVE app.
Members save 10% on Travel Insurance*
National Seniors members receive a 10% discount on travel insurance policies*.
Financial Information Consultant
Speak to a real person and receive up-to-date information on retirement planning, superannuation, and more!
Branches
Expand your social circle, enjoy social events, day trips, guest speakers, and meet like-minded members.
Exclusive Travel Discounts
Save on tours, cruises, and holidays with exclusive discounts on National Seniors Travel.
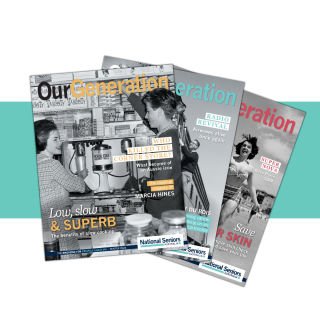
Our Generation Digital Magazine
Receive a yearly subscription to Our Generation Digital Magazine.
The Good Guys Commercial
Members enjoy exclusive access to The Good Guys Corporate Benefits. Save on small and large appliances as well as technology.
Advocacy & Research
Your membership directly funds our advocacy and research work fighting issues that affect you.
Competitions
Access exclusive member-only weekly competitions including books, DVDs, CDs, movie tickets and more.
Discounts
In addition to the discounts app, members can save thousands on eGift Cards and other discounted products.
*The discount applies to the total National Seniors travel insurance premium and is for National Seniors Australia members only. Discounts do not apply to the rate of GST and stamp duty or any changes you make to the policy. AGA has the discretion to withdraw or amend this discount offer at any time. This discount cannot be used in conjunction with any other promotional offer or discount.
For Travel Insurance policies purchased before 8 September 2026
National Seniors Australia Ltd ABN 89 050 523 003, AR 282736 is an authorised representative of nib Travel Services (Australia) Pty Ltd (nib), ABN 81 115 932 173, AFSL 308461 and act as nib's agent and not as your agent. This is general advice only. Before you buy, you should consider your needs, the Product Disclosure Statement (PDS), Financial Services Guide (FSG) and Target Market Determination (TMD) available from us. This insurance is underwritten by Pacific International Insurance Pty Ltd, ABN 83 169 311 193.
For Travel Insurance policies purchased on or after 8 September 2026
National Seniors Australia Ltd ABN 89 050 523 003, AR 282736, is an authorised representative of AWP Australia Pty Ltd, ABN 52 097 227 177, AFSL 245631, trading as Allianz Global Assistance (AGA), and acts as AGA's agent and not as your agent. nib Travel Services (Australia) Pty Ltd (nib), ABN 81 115 932 173, AFSL 308461 acts as third party administrator on behalf of AGA, managing claims, complaints, enquiries and sales. This is general advice only. Before you buy, you should consider whether the product is appropriate for you, the Product Disclosure Statement (PDS), Financial Services Guide (FSG) and Target Market Determination (TMD) is available from us. This insurance is underwritten by Pacific International Insurance Pty Ltd, ABN 83 169 311 193, AFSL 523921.